
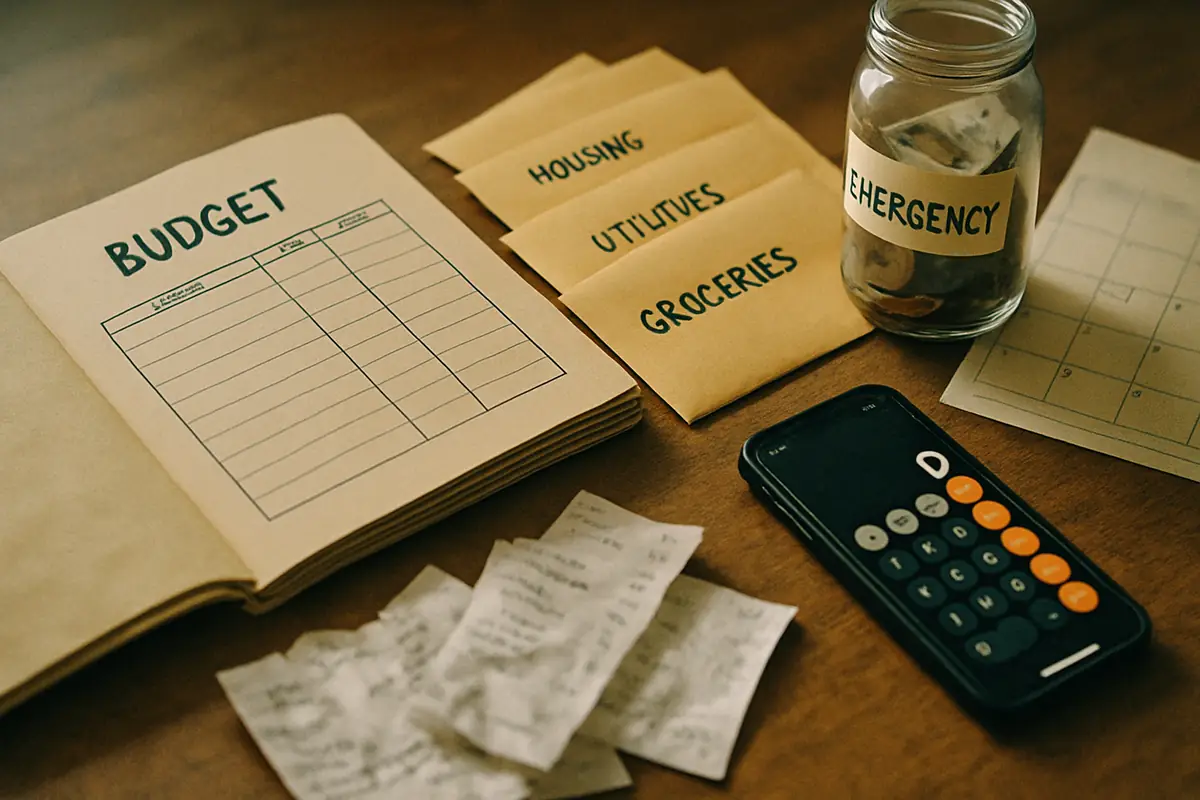
On a rainy Monday evening, Emma checks the family's envelope-style budget notebook while her partner sorts through receipts from that weekend’s grocery trip. Their monthly cash flow feels tighter than usual, but neither wants to dive into credit card debt for everyday expenses. They are determined to shift their financial habits gradually, balancing practical savings with life’s unpredictable moments.
Why Changing Money Habits Is Hard for Many Households
Changing financial behaviors is rarely straightforward. Households often face conflicting pressures: juggling income variability, unexpected expenses, and everyday living costs. For example, many families report feeling stressed when bills arrive close together or when income doesn’t come at regular intervals. The challenge increases when attempting to both reduce debt and build savings simultaneously. It's common to see emergency savings covering only one to two months of expenses instead of the recommended three to six months, making unplanned costs a source of anxiety rather than security.
Moreover, behavioral inertia—our tendency to stick with familiar choices—plays a key role. A household used to flexible spending may find it difficult to adopt strict budgeting envelopes or automated savings without a clear system and motivation. Small wins can feel rare when inflation pushes grocery bills up by 5% or more annually, squeezing margins further. Understanding these pressures helps reframe financial improvement efforts as gradual and adaptive rather than sudden or perfect.
Scenario: The Johnsons’ Journey Toward Better Money Management
How this can look in practice
The Johnson family balances two incomes totaling about $5,200 monthly after taxes while managing a mortgage of $1,250 and car payments near $450. Recent utility hikes added $75 monthly and food prices have nudged groceries up by about $100 each month this year. Over the past six months, their credit card balance climbed to $3,000 with an APR (annual percentage rate) near 22%, making minimum payments take over half their discretionary income some months.
Recognizing the financial stress, they decided on a behavioral change strategy that included setting up an automatic transfer of $300 monthly into a new emergency savings account and adopting the envelope budgeting method for variable expenses like dining out and entertainment. They also committed to reviewing expenses weekly rather than monthly to catch small leaks early.
This shift wasn’t easy; they encountered moments of friction balancing social activities and budget limits. Yet, by breaking goals into manageable steps—such as reducing credit card utilization from 70% of their available credit down toward 30%, which can positively impact credit scores—they gradually improved confidence in managing money flows.
How Behavioral Change Techniques Support Financial Skill Building
Behavioral change techniques create structure around decision-making processes that may otherwise feel overwhelming or abstract. Using tangible practices such as goal setting, monitoring progress visually (for instance, marking off weeks on a calendar when budget goals are met), and rewarding small successes help reinforce positive habits.
"Implementation intentions"—specific plans like "on payday I will transfer $250 to savings before paying other bills"—turn intentions into actions. This reduces reliance on willpower alone and leverages consistent decision triggers embedded in daily routines.
"Nudges," such as reminders or alerts timed around bill due dates or paydays, help maintain awareness without requiring aggressive self-monitoring all the time. Visual cues like sorting cash into labeled envelopes underpin the behavioral principle that seeing money set aside feels more real than tracking numbers on screens alone.
"Loss aversion," the tendency to avoid losses more strongly than acquiring gains motivates households when debt increases cost dramatically over time. For example, carrying a $3,000 balance on a credit card with a 22% APR means paying nearly $550 in interest annually if balances are not reduced promptly—making it clear how small monthly discipline can save hundreds of dollars.
"What Are the Trade-Offs When Adopting New Financial Habits?"
"Safety versus flexibility" is a persistent trade-off in household money management. Prioritizing an emergency fund builds financial security but might reduce short-term spending freedom or delay non-essential purchases. Conversely, prioritizing flexibility can mean relying on credit cards more often or skipping savings contributions during tight months.
Where readers should be careful
Behavioral changes take time; expect setbacks when adjusting spending patterns or automating savings transfers. Avoid discouragement if progress seems slow—consistent effort over months yields steady improvement rather than overnight fixes.
Benefits of Behavioral Change Techniques in Household Finance
- Creates clearer visibility into spending habits through categorization and tracking.
- Encourages gradual adjustments less likely to trigger overwhelm or resistance.
- Builds momentum via small wins enhancing motivation.
- Reduces reliance on memory or willpower by embedding routines.
- Improves emergency fund accumulation aiding financial resilience.
Potential Challenges When Applying These Techniques
- Takes patience; immediate results are uncommon leading some to give up prematurely.
- Rigid systems may feel constraining if life situations change suddenly.
- Initial setup requires effort — tracking expenses accurately can be tedious.
- Behavioural fatigue can occur if too many changes happen simultaneously.
- Savings automation may cause temporary cash flow tightness requiring careful timing.
Practical Example: Calculating Interest Savings by Reducing Credit Card Debt
Consider the Johnsons’ situation with a $3,000 credit card balance at an APR of 22%. Minimum monthly payments on such cards often equal about 2%–3% of the balance — here roughly $90 per month (3%). If they only pay the minimum each month without new charges, interest accrues rapidly: approximately $55 per month ($3,000 x 22% ÷ 12). Over one year with no balance reduction, interest totals around $660 — meaning they would pay nearly $4,000 total including principal but have little progress lowering debt.
If instead they increase monthly payments by an extra $150 toward principal ($240 total), interest reduces because the principal drops faster. After six months making these higher payments consistently:
- Their balance falls from $3,000 to about $1,650 (6 x ($240-$55)).
- This lowers monthly interest charged further since it's calculated on smaller balances.
- They save roughly $150 in interest over what would have been paid at minimum payments alone within this timeframe.
- And free up future cash flow sooner as principal decreases accelerate payoff speed.
This worked example highlights how small increases in payment amounts combined with steady behavior changes can yield meaningful cost savings over time.
Key Steps for Households Starting Behavioral Changes Today
Start by tracking all income sources and fixed expenses such as rent/mortgage and utilities for at least one month without altering anything yet. This realistic baseline provides insight into true cash flow patterns including irregular bills or seasonal costs. Next, categorize discretionary spending like dining out or subscriptions where small cutbacks add flexibility.
Set concrete goals using simple rules: aim first for building a starter emergency fund around $1,000 or one month's essential expenses while maintaining minimum debt payments. Automate transfers shortly after paydays so saving happens before temptation strikes. Use envelopes—physical or digital—to allocate spending limits clearly by category each month.
Review progress weekly with your household members to discuss challenges openly rather than avoiding them until monthly statements arrive stressed and surprised. Adjust budgets flexibly recognizing compromises needed between control and quality of life improvements.
Where readers should be careful
Beware of relying solely on credit cards when establishing new habits; increasing utilization above roughly 30%-40% of your available limit can damage your credit score even if payments remain timely.
Balancing Security and Flexibility: What Does That Look Like Practically?
For many households, balancing safety nets against day-to-day enjoyment means accepting messier budgets some months while preserving buffer amounts for emergencies or occasional splurges without guilt. For instance, earmarking about 10%-15% of income for flexible use while devoting necessary portions toward essentials and essentials debt service keeps priorities clear but adaptable.
When inflation rises by typical rates between 3%-7% annually as seen recently in groceries or fuel prices compared against stagnant income growth scenarios common for certain professions—the tension between saving more versus maintaining lifestyle intensifies considerably. Behavioral skills include negotiating this trade-off thoughtfully rather than abandoning plans outright during tougher times.
Advantages of Balancing Security with Flexibility in Household Budgets
- Enhances resilience against unexpected shocks without resorting immediately to high-cost borrowing.
- Preserves psychological wellbeing by allowing controlled discretionary spending.
- Acknowledges real-life unpredictability promoting sustainable habit formation over time.
Drawbacks To Monitor When Striving For Balance
- Might slow overall wealth-building pace if flexibility consistently trumps saving priorities.
- Increased complexity could overwhelm some households lacking clear systems or communication.
- A tempting excuse for delaying difficult but necessary expense reductions in certain cases.
Returning To Emma And Her Partner: Reflections After Three Months
Emma notices their envelope system gave surprising clarity about weekend entertainment choices—knowing exactly how much was left helped postpone some outings without feeling deprived outright. Their emergency fund reached approximately $1,200 after three transfers averaging around $400 each month since starting—a welcome reassurance amid recent job schedule changes causing income shifts from week to week.
They acknowledge occasional frustration when sticking rigidly prevented attending spontaneous family events but cherish increased peace knowing they are reducing high-interest debts steadily—in particular cutting down the previous credit card balance from nearly $4,500 last fall to under $2,800 now thanks to extra payments prioritized after budget reviews.
Their story exemplifies how behavioral change techniques embedded within ordinary household routines provide achievable pathways toward better financial management skills—not through radical upheaval but through honest compromises founded in realistic expectations about timing, trade-offs, and evolving priorities.
Leveraging Habit Formation to Enhance Financial Discipline
One of the most effective behavioral change techniques for improving financial management skills is habit formation. By establishing consistent routines around budgeting, saving, and spending, individuals can automate positive financial behaviors, reducing reliance on willpower alone. For instance, setting up automatic transfers to savings accounts immediately after payday ensures that saving becomes a non-negotiable habit rather than an afterthought. Over time, these small but consistent actions contribute to significant financial stability. Habit formation aligns with the brain’s natural preference for routine, making it easier for people to stick with good money habits without feeling overwhelmed by daily decisions.
Moreover, breaking down larger financial goals into smaller, manageable actions helps reinforce these habits. Instead of aiming to save a large lump sum in a short period, individuals can commit to saving a fixed amount each week or each paycheck. This approach not only makes the goal feel more achievable but also leverages the psychological effect of accumulating small wins. Celebrating these incremental successes can further motivate individuals to maintain their habits and build momentum toward larger financial objectives.
Another practical method is habit stacking—linking new financial behaviors onto existing habits. For example, pairing the act of reviewing monthly expenses with a regular activity such as morning coffee can create natural cues that trigger the desired behavior. These contextual cues help solidify new financial routines by embedding them within familiar daily patterns, increasing the likelihood of long-term adherence.
Harnessing Behavioral Nudges to Encourage Smart Financial Decisions
Behavioral nudges are subtle modifications in the environment or presentation of choices that steer individuals toward better financial decisions without restricting freedom. For example, default options like enrolling employees automatically in retirement savings plans capitalize on inertia to increase participation rates. Similarly, apps that provide real-time feedback on spending or highlight potential savings opportunities gently nudge users toward more mindful money management.
Designing nudges requires understanding common cognitive biases that affect money decisions. Loss aversion, where people fear losses more than they value gains, can be addressed by framing saving as avoiding future loss rather than just accumulating wealth. Another bias is present bias—overvaluing immediate rewards over future benefits—which can be mitigated by creating immediate gratification through rewards or gamification for meeting financial milestones.
Incorporating reminders and timely prompts also serves as an effective nudge. For instance, sending notifications before bills are due encourages on-time payments and avoids penalties. Likewise, highlighting how current spending compares with personal budgets or peer averages can create social proof pressures that influence behavior positively. These nudges work best when tailored to individual preferences and circumstances, ensuring relevance and maximizing impact.
The Role of Self-Monitoring and Reflective Practices in Financial Growth
Self-monitoring involves tracking one’s own behaviors and outcomes to increase awareness and promote accountability—critical components in mastering financial management. Tools such as expense trackers, budgeting apps, or simple journals enable individuals to gain insights into spending patterns and identify areas needing improvement. Regular reflection on these data points fosters intentionality rather than reactive decision-making.
Reflective practices might include weekly reviews of finances where individuals assess whether they stayed within budget, evaluate progress toward goals, and consider adjustments needed for the upcoming period. This structured reflection encourages proactive planning and reduces impulsivity often triggered by emotional or situational factors.
Additionally, combining self-monitoring with goal-setting amplifies effectiveness. Setting SMART (Specific, Measurable, Achievable, Relevant, Time-bound) goals provides clear targets against which progress is measurable during reflections. As individuals observe improvements or setbacks over time, they can recalibrate strategies accordingly—a dynamic process that strengthens resilience and adaptability in managing finances.






